
Tubarão’s Middle Tonnage Is Paying for Someone Else’s Priority
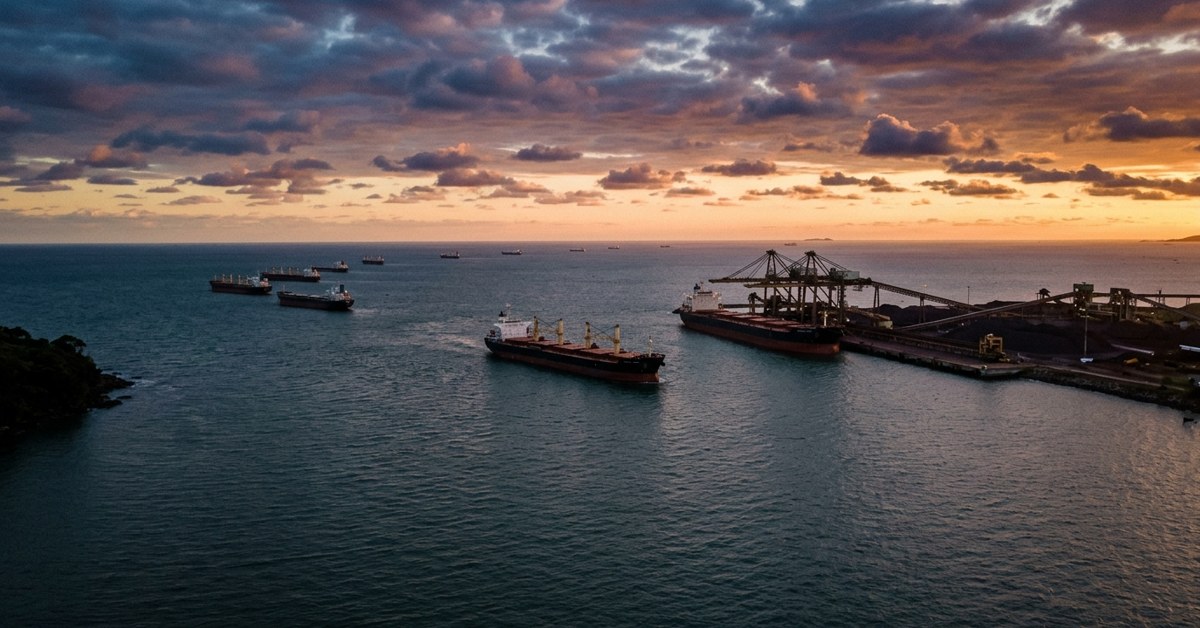
Our own AIS data on Tubarão shows something that doesn't line up with a simple rain story. Panamax and Kamsarmax median waiting time went from 87.8 hours in September to 232.7 hours in October (our liman_benchmark data, n=18 and n=8). Supramax and Handymax moved from 75.7 to 215.2 hours. Ultramax went from 92.6 to 196.7 hours. That's roughly two to three times the wait, across three separate size classes, in one month.
Newcastlemax and VLOC tonnage barely moved: 31.0 hours in September, 41.3 in October. If this were rain closing the port, it would hit every segment roughly the same way. It didn't. El Niño rainfall forecasts for the Tubarão area are weak and inconsistent this month, not the kind of signal that explains a jump this size.
What probably did move is volume. Vale's shipments from Tubarão to China ran 15% above 2025 and 41% above 2024 for the January-August period, according to Hellenic Shipping News and Cyprus Shipping News coverage of the Capesize market. Our read on the AIS numbers: the terminal likely keeps its dedicated Capesize/VLOC berths running on schedule because those are the big, planned parcels, while Panamax, Supramax and Ultramax cargoes queue behind them. The ships that haven't gotten slower are the ones with their own line.
Meanwhile the freight side tells a separate story. Tubarão-Qingdao Capesize fixed at $30.10-31.45/mt in Week 43 (SSY Atlantic Capesize Index / Advanced Shipping & Trading Weekly, 23 October), down 11.3% from the start of the month and 20.9% below late September (IndexBox/Hellenic Shipping). Tubarão-Rotterdam printed $11.85/mt, Tubarão-Japan $29.80/mt. TCE on the Rotterdam leg sits around $12,825/day against a $33,900/day ballast return from China to Brazil (Xclusiv Shipbrokers Weekly, Week 43). Our own AIS sample for Capesize waiting time in October is only 2 vessels, too thin to call a number on, so we're leaving it out of the comparison rather than guessing.
For anyone fixing Panamax, Supramax or Ultramax tonnage into Tubarão right now, September-based laycan assumptions are already out of date. Build in two to three extra days on top of the old median, and price demurrage risk accordingly in these three segments specifically, not across the board.
Baltic Dry Index closed 28 October at 2,652 (+49, +1.9%), snapping a three-day slide. Panamax fell 2.8% the same session, so we're not calling it a trend reversal yet (tradingeconomics.com/commodity/baltic).