
Scrap Steady in the Med, Handysize Stuck at the Floor
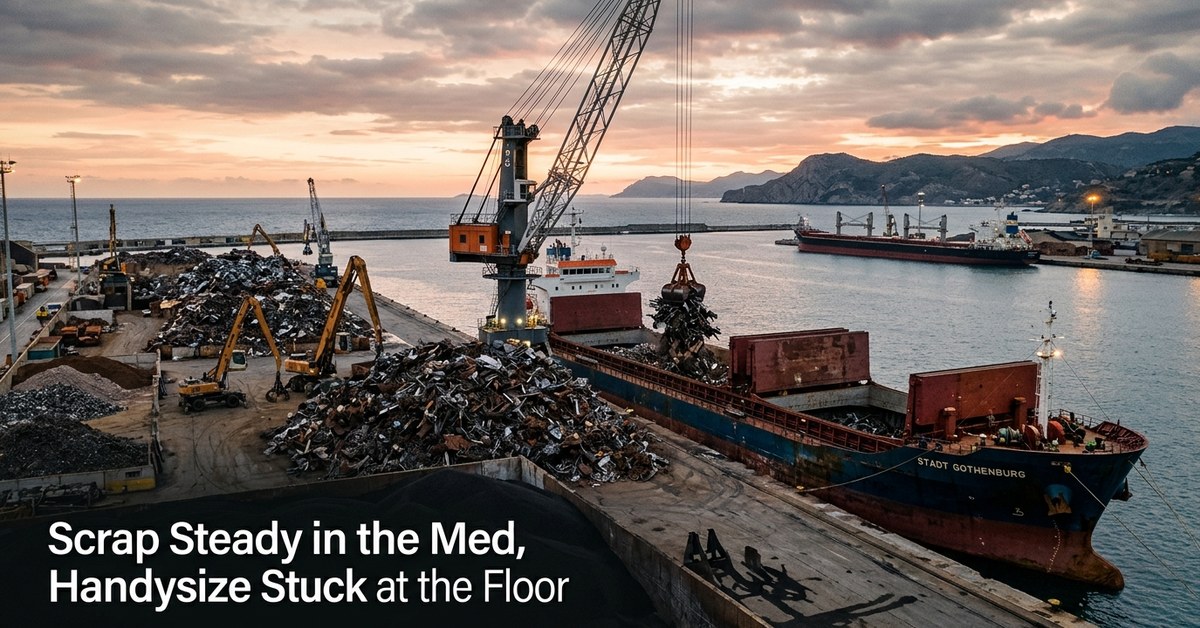
Steel scrap is one of the few corners of the dry bulk market that moves on its own schedule. Mill demand, collection costs and regional stock levels drive it more than the iron ore or coal headlines that usually set the tone for bulk freight, and this week's numbers make that split obvious.
The Baltic Handysize Index closed at 1,014 on 2 November, exactly where it has sat for close to three weeks (handybulk.com). Capesize dropped 4.0% over the same period to 3,963, and Panamax and Supramax eased slightly too. Handysize simply isn't reacting to the same pressure. The Baltic Exchange's Week 44 report (via drybulkmagazine.com) points to why: Continent scrap rates have moved into the low $30,000s a day, the Eastern Mediterranean is more active than the West, and a 63,000 dwt ship delivering Tyne fixed at $38,000 a day for an East Med scrap run.
We're seeing the same pattern in our own fixtures. A Handysize taken delivery Bremen, redelivery Turkish Med, loaded steel scrap at $28,000 a day on 3 November (ISM Weekly, Week 44). The same day, a coaster moved a scrap parcel (SF58) from ARAG to Nemrut at $53 per tonne. Both sit comfortably inside the range the Baltic report describes, and both point to a Mediterranean trade that's holding its own while bigger segments correct.
Turkey's import scrap market looks tight and steady this week too, with Baltic and EU-origin cargoes edging up slightly, according to SteelOrbis. That lines up with what the fixtures show: mills keep buying, and tonnage able to work the Black Sea and East Med corridor stays in demand even as broader sentiment softens elsewhere.
The wider backdrop helped owners rather than hurt them. Brent fell 8.1% to $104.28 and VLSFO in Singapore eased 1.6% to $1,003.50 (both via handybulk.com), which trims voyage costs without anyone needing softer freight to make a trade work. For now, scrap on the Handysize and coaster side looks like the one piece of the market running on its own logic, largely unbothered by what Capesize is doing.