
Capesize’s Weak Bounce
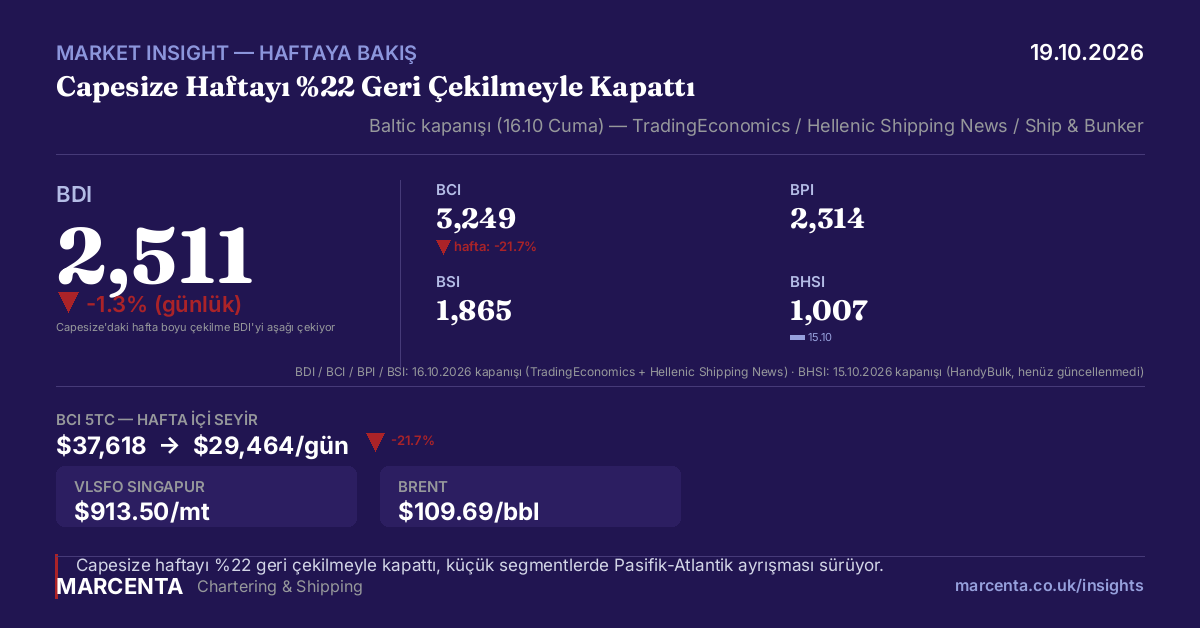
Baltic Exchange (via Hellenic Shipping News), Ship & Bunker, TradingEconomics — week of 12-16 October 2026.
The Capesize market spent most of last week sliding and only found its footing on Friday. The BCI 5TC opened Monday (12 October) at $37,618 and closed Friday (16 October) at $29,464, a drop of close to 22% over the week. C5 (West Australia-Qingdao) told the same story in miniature: $13.40 at the start of the week, down to $11.25 by Thursday, then back up to $11.70 on Friday after two miners came in for tonnage. That is not nothing, but it is not a turn either. Two fixtures covering a short window of tight prompt dates look different from fresh cargo demand picking up, and until next week's volume says otherwise we would read Friday as a pause rather than a floor.
C3 (Tubarao-Qingdao) moved from roughly $37.20 early in the week down into the $30-33 range by Friday, weighed down by the same mix of ample tonnage and soft bids seen across the Capesize board. We have our own data point here too: a Capesize fixture on the Tubarao-Qingdao run that we logged on 16 October came in at $30.75/mt, sitting right inside that Friday range. It is a small thing, but it is useful confirmation that what the Baltic reports and what is actually getting done in the market are lining up this time.
Panamax and Supramax had a steadier week, though not for the same reasons everywhere. The Pacific basin is pulling ahead of the Atlantic, with Australian and Indonesian coal and bauxite demand plus NoPac grain keeping rates firmer out east, while the Atlantic looks more balanced but is quietly building up tonnage. Our market desk reads this as the usual October-November seasonal pattern rather than a structural shift, so we would not extrapolate it too far into Q1. Handysize stayed calm, with the Continent and Mediterranean in balance, ECSA firming up, and the US Gulf still carrying excess tonnage.
On bunkers, VLSFO sat at $913.50/mt in Singapore, $740.50/mt in Rotterdam, and $967.00/mt in Fujairah as of Friday, with Brent at $109.69/bbl. One thing worth flagging for anyone fixing Gulf-loading dry bulk cargo this week: UKMTO logged five separate incidents in the Hormuz/Gulf area between 14 and 17 October. It is mostly a tanker and container story so far, but it is the kind of thing that belongs in a voyage risk conversation on fertiliser and grain liftings out of the region, not just an afterthought.
The question for this week is simple: does the Capesize bounce hold, or does the index keep sliding once the two miners who came in on Friday are done covering their positions.