
Capesize Holds Above $34,000 as Panamax Slides: Dry Bulk Market Insight, 26 October 2026
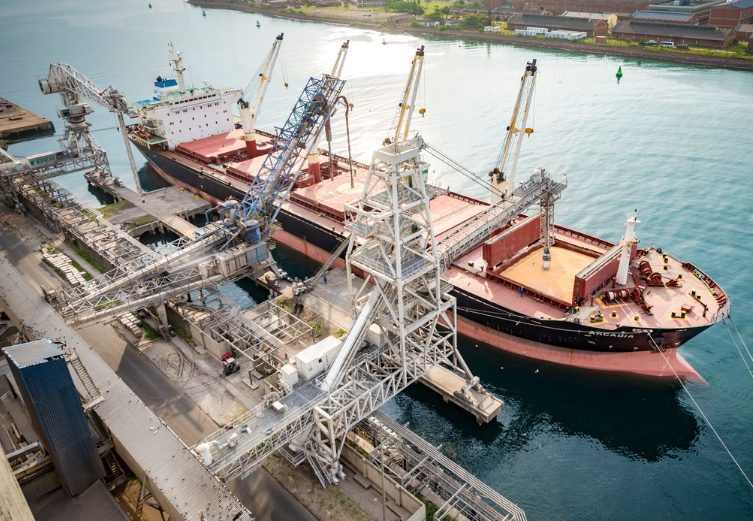
The Baltic Dry Index closed Friday 23 October 2026 at 2,660 points, down 33 points on the day, but the week as a whole belonged to the Capesize segment. The BCI finished at 3,791 and the 5TC average ended the week at $34,380 per day, up from $30,518 on Monday. Today is Monday, so Friday remains the latest published close; the first print of the new week is not yet available at the time of writing.
Baltic Indices: Friday 23 October 2026 Close
| Index | Close | Daily change | Avg. daily earnings |
|---|---|---|---|
| BDI | 2,660 | -33 | – |
| BCI (Capesize) | 3,791 | -57 | $34,380 (-$519) |
| BPI (Panamax) | 2,109 | -42 | $18,981 (-$377) |
| BSI (Supramax) | 1,887 | -3 | $23,849 (-$42) |
| BHSI (Handysize) | 1,020 | unchanged | $18,361 (+$4) |
Capesize gave back a little on Friday after four sessions of gains, but the weekly picture is firm: improving sentiment in both basins lifted the 5TC steadily from Monday to Friday. Panamax is the soft spot. The BPI has lost ground every session this week, with the Atlantic clearly the weaker basin as limited cargo replenishment and surplus tonnage favour charterers. Supramax and Handysize were essentially flat.
Capesize Routes: Week of 19-23 October 2026
In the Pacific, the West Australia to Qingdao iron ore route (C5) advanced from the low $12s to the $14.15-14.25 per tonne range by midweek, supported by renewed operator demand and miners covering early-November requirements. In the Atlantic, the Tubarao to Qingdao route (C3) moved from the low $31s to the $34.00-34.50 per tonne range as bids for forward dates climbed against limited offers, although talk of a lower fixture for mid-November cooled sentiment towards the close. Demand is now concentrated on end-November and split November-December dates.
Bunkers: Friday 23 October 2026
| Port | VLSFO ($/mt) | Change | MGO ($/mt) | Change |
|---|---|---|---|---|
| Singapore | $963.00 | +26.00 | $1,351.50 | +10.50 |
| Rotterdam | $766.00 | +3.00 | $1,446.00 | +11.50 |
| Fujairah | $981.00 | +12.00 | $1,768.50 | +17.50 |
Fuel costs rose across all three hubs. Singapore VLSFO added $26 on the day and now trades within $18 of Fujairah, while Rotterdam remains the cheapest of the three at $766. For owners and operators, the firmer fuel cost takes a visible bite out of the Capesize earnings gain, particularly on longer Atlantic-to-Pacific voyages where consumption is highest.
Brent
Brent crude is quoted at $115.39 per barrel at the time of writing. With oil holding at these levels, bunker prices are likely to stay elevated in the near term, keeping voyage break-evens under pressure even where freight is improving.
Market Developments
- Panamax Atlantic weakness: Transatlantic activity lost momentum through the week and fronthaul business came under pressure as owners repeatedly lowered expectations. The Pacific proved more resilient, with healthy Australian demand underpinning sentiment.
- Supramax split: The US Gulf softened as new enquiries failed to keep pace with a lengthening tonnage list, while Asia remained the main driver of the segment.
What We Are Watching
- Whether Monday’s Capesize print holds above the $34,000 level or the Friday dip extends.
- Whether C3 can hold the $34 area as end-November dates are covered.
- Panamax Atlantic cargo flow and whether the BPI finds a floor.
- The impact of Brent above $115 on bunker costs and voyage break-evens.
Market views are indicative and for information only. Contact Marcenta Chartering and Shipping for specific fixture enquiries.