Baltic Dry Index Closes Week 32 at 3,089 as Capesize Leads a Broad Market Rally
Dry bulk freight closed Week 32 on a firm note, with the Baltic Dry Index climbing from around 2,843 points at Monday's open to 3,089 by Friday's close, an advance of roughly 8.6% over the week. The move was broad in scope but Capesize-led: bigger ships did the heavy lifting while the smaller segments delivered a far more mixed picture, with Panamax firming, Supramax roughly flat, and Handysize easing.
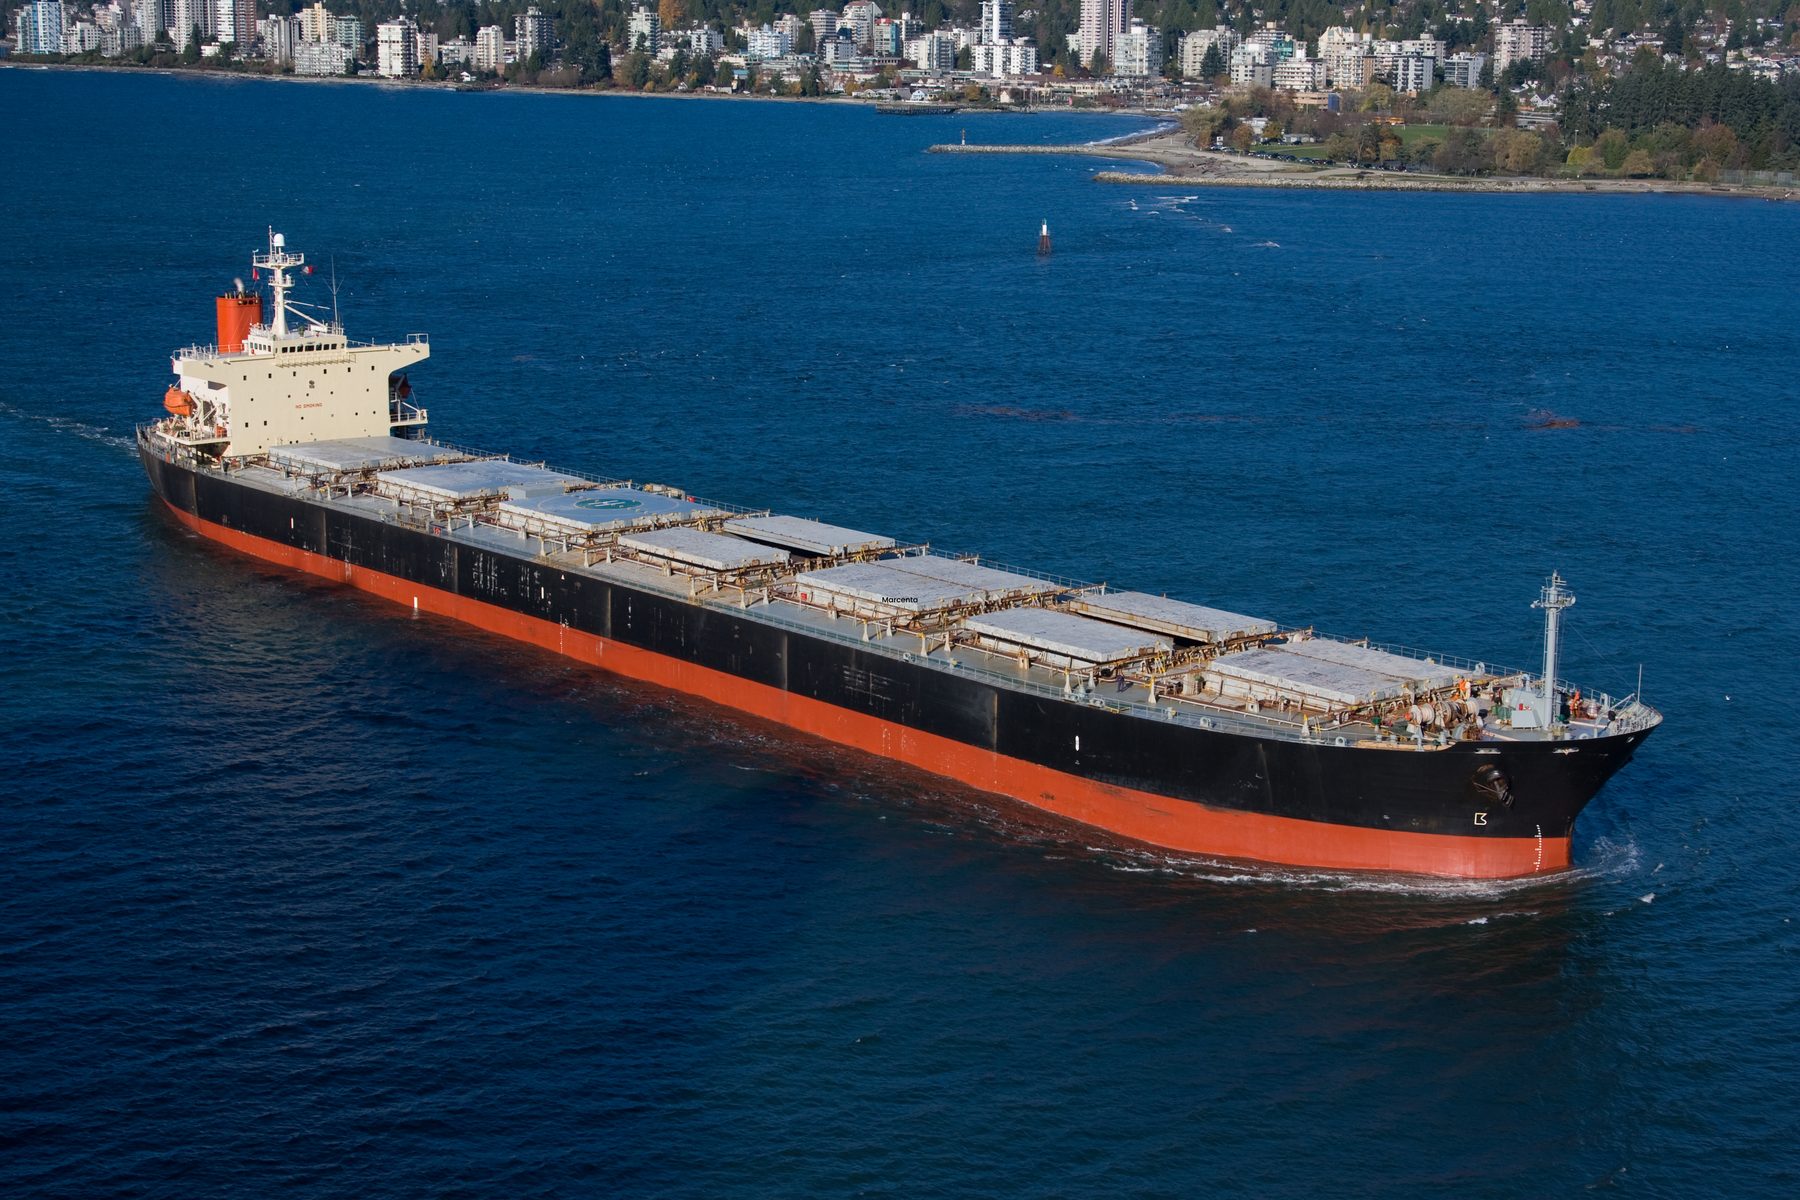
Capesize. The BCI 5TC average moved from about $41,395 to $46,512 across the week, and the benchmark C5 route (Western Australia–Qingdao) firmed from around $14.50 to $16.50 per tonne by Friday. C3 (Tubarao–Qingdao) also edged higher to roughly $36.00 per tonne. Pacific tonnage tightened as owners held firm on rates into the weekend, and brief loading delays linked to Typhoon Dolphin off the Chinese coast added a supportive undertone without materially disrupting the fixture flow.
Panamax. The BPI added ground through the week to finish at 2,298, with the average TCE up to roughly $20,684. Transatlantic and ECSA fronthaul business improved on steady South American grain demand, while Pacific NOPAC fixtures also firmed. Brokers reported an 81,000 dwt kamsarmax fixed in the low-$30,000s for a USEC–WCI trip via ECSA, illustrative of the tone across the basin as the week progressed.
Supramax / Ultramax. The BSI eased marginally, down 5 points to 1,603, with the 11TC average around $20,258. The US Gulf firmed late in the week, with larger ultramax stems reported near $28,000, while Pacific business softened — Singapore–Indonesia–China runs slipped from roughly $18,000 to $15,500 as fresh enquiry thinned into the weekend.
Handysize. The BHSI slipped 2 points to 874, with the average TCE around $15,729. Continent/Mediterranean and ECSA fronthaul activity was mixed, Skaw–Gibraltar softened modestly, and Asian handysize demand stayed muted on limited fresh cargo, keeping the segment the weakest performer of the week.
Outlook. Heading into Week 33, sentiment remains supported by tightening Capesize tonnage in the Pacific, though the aftermath of Typhoon Dolphin and China's iron ore stockpile trend are worth watching for early direction. The smaller segments look set to stay broadly rangebound absent a fresh push from grain or coal demand.
Sources: Baltic Exchange, HandyBulk, Ship & Bunker. This article is for general market information only and does not constitute freight advice; for a fixture-specific read, contact the desk directly.