Baltic C3 and C5 Just Diverged — Here’s What the Split Actually Tells Owners and Charterers
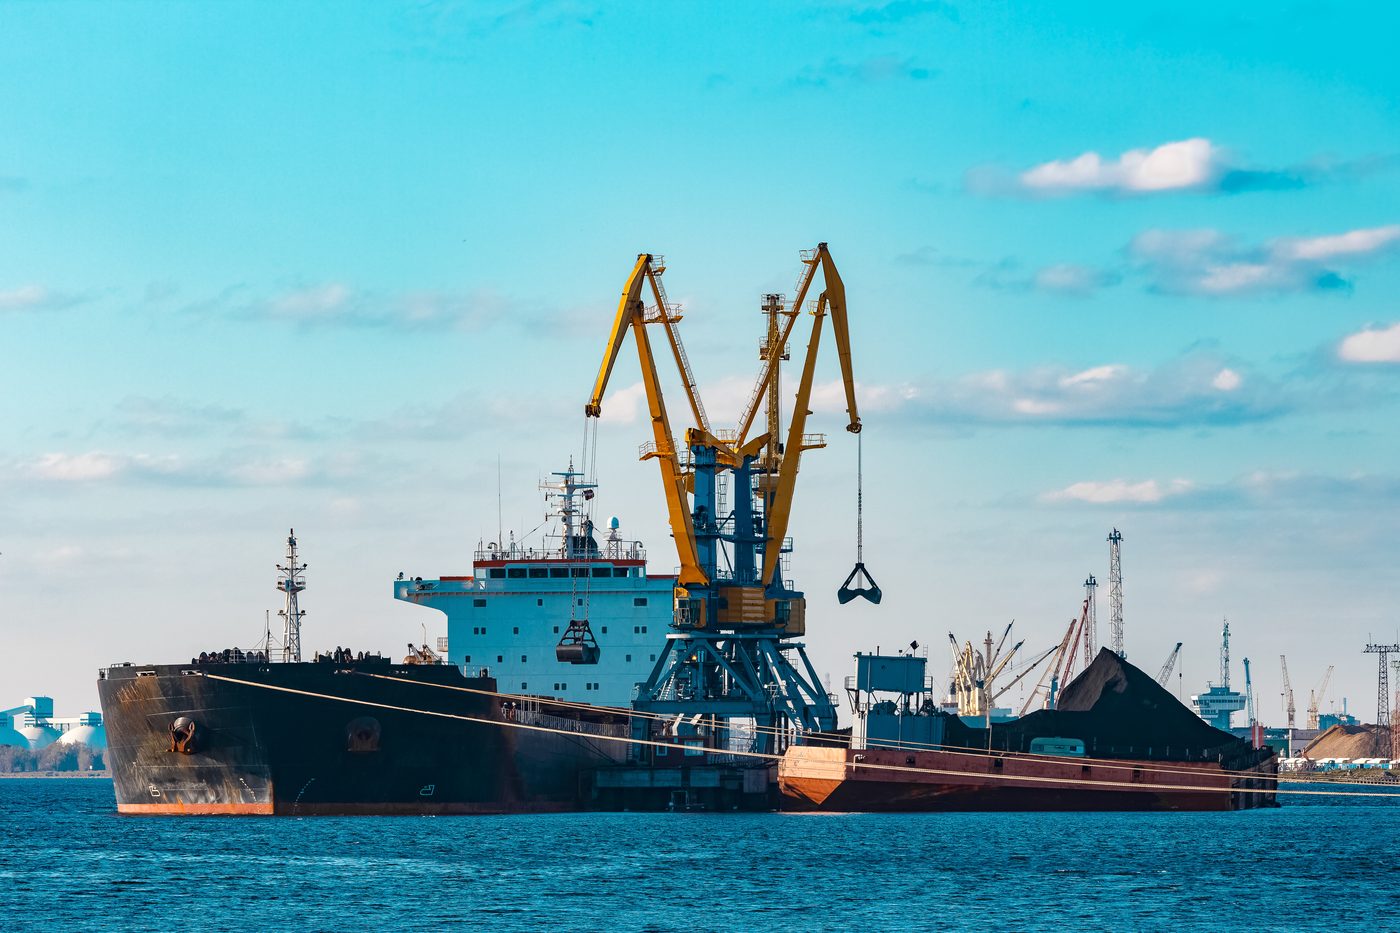
Two of the most closely watched numbers in dry bulk shipping just moved in opposite directions, and the reason why is more useful than the numbers themselves. In its Week 33 roundup, the Baltic Exchange reported that C5 (West Australia–China) retreated sharply from above $16 to $14.110 per tonne by the close, while C3 (Brazil and West Africa–China) held firm, fixing around $35 to $36 per tonne despite thinner overall engagement. For anyone outside the Capesize market, that split can look like noise. For owners and charterers, it is actually one of the clearest signals the market gives about where tonnage is tight and where it is not.
What Baltic C3 and C5 Actually Measure
C3 and C5 are two of the Baltic Exchange’s benchmark Capesize voyage routes, and together they cover the two main iron ore corridors into China. C3 prices a roughly 170,000-tonne cargo of iron ore from Tubarao or West Africa to Qingdao — the Atlantic route, dominated by Brazilian exporters. C5 prices the equivalent cargo from Western Australia to Qingdao — the Pacific route, dominated by Australian miners. Both are assessed daily by a panel of shipbrokers and published in $/tonne, and both feed directly into the Baltic Capesize Index (BCI) and the FFA derivatives market that owners and charterers use to hedge freight risk. Because Brazil and Australia are the two dominant iron ore sources for Chinese steel mills, C3 and C5 between them capture the large majority of Capesize demand.
Why the Two Routes Just Split
This week’s divergence came down to tonnage balance rather than cargo demand. On the Pacific side, an expanding list of available ships — partly vessels returning to service after the previous week’s weather disruptions — met a Chinese miner presence that improved but was not enough to absorb the extra supply, so owners ended up competing for a limited number of West Australia cargoes and C5 corrected sharply into the weekend. On the Atlantic side, the opposite was true: a comparatively tight ballaster list and relatively strong first-half-September loading demand out of Brazil kept C3 firm even though fewer fixtures were being reported. The lesson is the same every time this happens — when one basin has more open tonnage than cargo and the other does not, the routes stop moving together, and the spread between them widens.
What the Spread Means for Positioning Decisions
A widening C3–C5 spread is a practical signal, not just a data point. For an owner deciding where to ballast an open Capesize, it points toward the tighter basin — currently the Atlantic — as the better place to be positioned for the next fixing window. For a charterer, it is a reminder that a single Baltic Dry Index headline can mask very different conditions underneath, which is exactly why we look at route-level data rather than the index alone when advising clients on Capesize positioning or structuring owner representation around a specific loading region. If the spread keeps widening into next week, expect ballasters to start favouring the Atlantic in greater numbers, which would in turn start to narrow the gap again.
Sources: Baltic Exchange Weekly Roundup – Bulk Report Week 33, HandyBulk Baltic Dry Index. This article is for general market information only and does not constitute freight advice; for a fixture-specific read, contact the desk directly.