
The Baltic Dry Index Stopped Falling. Panamax Didn’t Get the Memo.
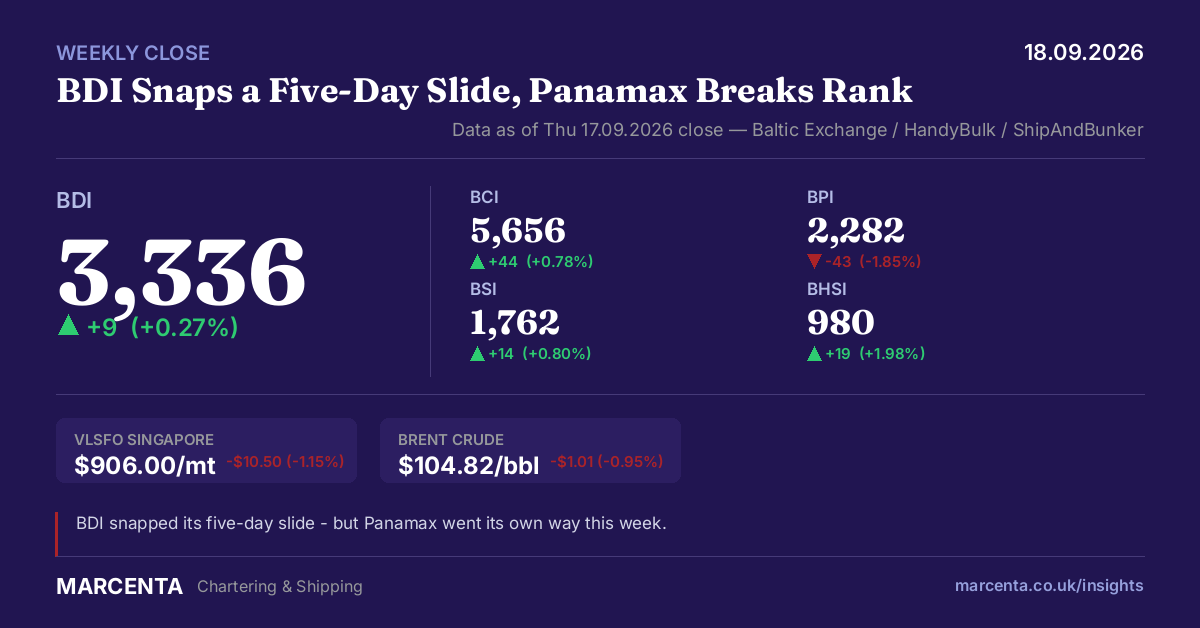
Dry Bulk Insights, Market InsightThe Baltic Dry Index closed the week at 3,336 on 17 September, up 9 points and ending a five-day losing run, according to handybulk.com’s daily Baltic Dry Index data. Capesize did the heavy lifting: the BCI rose 44 points to 5,656, with average daily earnings around $51,296. Handysize and supramax also firmed, up to 980 and 1,762. Panamax went the other way, down 43 to 2,282, with daily earnings near $20,535.
The split matters more than the headline. Hellenic Shipping News reported this week that Chinese steel mills stepped up seaborne iron ore buying ahead of the Golden Week holiday (1–7 October), which lines up with capesize’s move. The same outlet’s panamax coverage points to the opposite problem: ton-mile demand down 6.9% year on year, tonnage supply up 2.1%, pushing the demand-to-supply ratio to 0.91. One index, two different stories, and neither one is really about the same cargo.
Worth flagging: the C3 (Tubarao–Qingdao) and C5 (West Australia–Qingdao) benchmark routes barely moved this week, holding around $41.5–42.0/mt and $17.9/mt respectively. If China’s restocking push were already showing up in physical iron ore freight, we’d expect to see it there first. It hasn’t yet, which suggests the capesize index gain is running ahead of the spot market rather than confirming it. A week ago, Hellenic Shipping News described the dry bulk market as enjoying its best run in five years, with C5TC touching roughly $54,791/day on 4 September, the strongest since October 2021. That level has since eased, and this week’s flat spot rates are one reason to treat the recovery as seasonal rather than structural for now.
On the cost side, VLSFO in Singapore rose from $854.50 to $906.00/mt over the week (bunkerindex.com), even as Brent slipped from $107.63 to $104.82/bbl (tradingeconomics.com/bunkerindex.com). Higher bunker against a softening oil market is an odd combination and worth watching into next week, particularly for longer capesize legs where fuel is the largest single voyage cost.
What we’re watching over the weekend and into next week: whether capesize gives back its gains once China’s Golden Week buying tapers off; whether panamax’s supply-driven weakness spreads to other segments if it continues; and whether C3/C5 spot rates eventually catch up to the index move, or the index move fades first.