
Market Insight — 08.09.2026
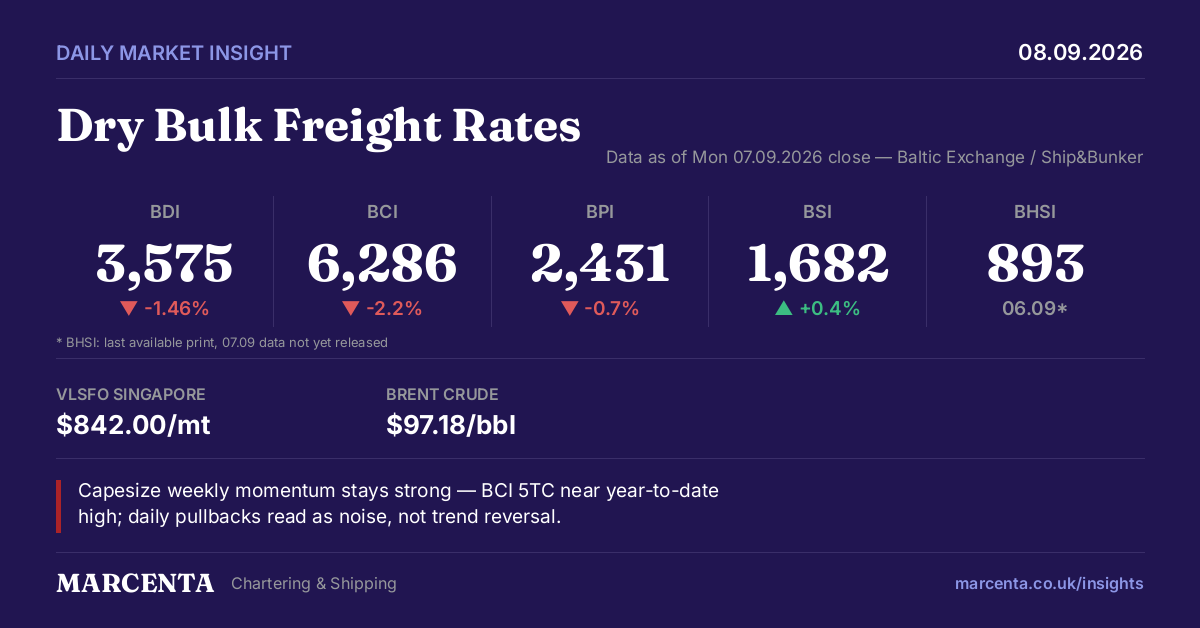
Dry Bulk Insights, Market InsightThe Baltic Dry Index closed at 3,575 on 7 September, down 1.46% on the day and continuing a choppy three-session run — 3,628 on Thursday, 3,488 on Friday, back up to 3,575 on Monday. Capesize led the daily move down, off 2.2% to 6,286 points. Read in isolation, that looks like the segment losing steam. It isn’t.
Zoom out to the week and the picture flips. Capesize 5TC broke above $58,000/day, a level not seen so far this year, and the C3 Brazil-China route climbed from $38.80 to $41.50/mt. Miner activity behind that move has been consistent rather than a one-off spike. Daily index closes react to the last few fixtures reported; the weekly trend reflects the actual order book charterers are working through. For owners with Capesize tonnage open in the Atlantic, the daily dip is not a signal to chase rate — the fixture activity underneath it says the opposite.
Panamax sat closer to flat, down 0.7% to 2,431, with demand described as solid on both the Atlantic and Pacific side. That two-basin balance matters more than the single-day print: it means owners aren’t relying on one region to absorb tonnage, which tends to support rate stability rather than a sharp move either way. Supramax ticked up 0.4% to 1,682 — a small move, but a rare green print in a session where most of the index was red.
Bunker costs moved in different directions across hubs — VLSFO softer in Singapore and Fujairah, marginally firmer in Rotterdam — none of it large enough to shift voyage economics on its own. Brent held at $97.18/bbl. Handysize has no fresh print for the session; the last available reading is 893 points from 6 September, so we’re not treating it as current data.
The practical takeaway: don’t read a single day’s BDI move as the market’s direction. This week, the more useful number was the weekly Capesize TC, not the daily index close.
Source: Baltic Exchange indices and BCI route commentary via handybulk.com (Baltic Dry Index page), close of 7 September 2026 (Handysize: 6 September 2026, no fresher print available); bunker prices via shipandbunker.com.