
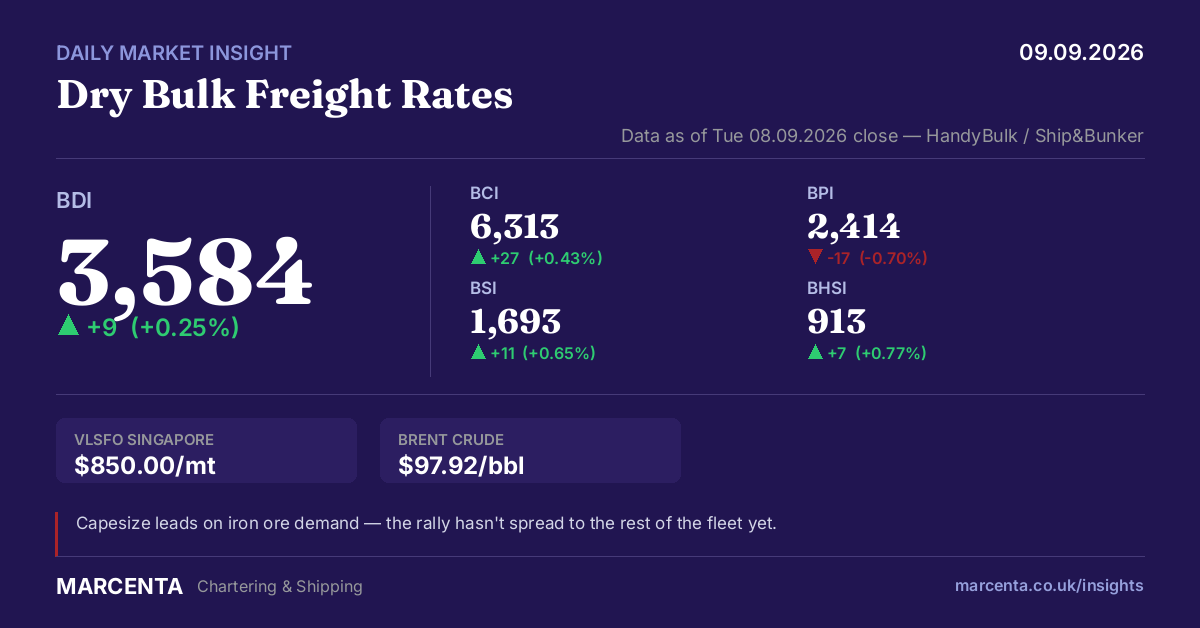
Capesize Pulls Away From the Rest of the Pack, and Iron Ore Is Why
Dry Bulk Insights, Market InsightThe Baltic Dry Index closed Tuesday at 3,584, up 9 points, but that headline number hides a split market. The Capesize index added 27 points to 6,313, with average daily earnings on the benchmark 5TC basket up to $57,253. Panamax went the other way, down 17 points to 2,414, average earnings off $154 to $21,724. Supramax and Handysize both edged higher but barely: 11 and 7 points respectively. One segment is moving. Three aren’t.
The clearest read on why sits in our own fixture records. Doric reported a Capesize fixed at $37.50/mt on the Tubarão–Qingdao run, laycan 07 October. Today’s C3 spot assessment for the same route is $41.50, up from $38.80 at the start of the week. So an owner just agreed to load a month from now for roughly 10% less than what the route pays today. That’s backwardation, plain and simple: the forward book is priced cheaper than the spot market, which only makes sense if the owner expects October rates to have eased by the time the ship arrives. Two more Doric fixtures back this up. Port Hedland–Qingdao went for $15.50/mt (September 9 laycan) and Dampier–Qingdao for $14.90/mt (September 11), both roughly in line with C5’s reported move from $15.50 to $18.90 over the same week.
Capesize strength this pronounced, without Panamax or Supramax following, usually means the demand is commodity-specific rather than a general dry bulk pickup. Capesize earns its premium hauling iron ore over long distances — Brazil to China is around 11,000 nautical miles — and that ton-mile effect doesn’t touch the smaller segments the same way. Bunker costs (VLSFO Singapore at $850/mt, Brent at $97.92) aren’t doing anything unusual to explain the gap either.
Worth noting: we don’t have a clean read from our own port data on whether congestion is adding to the squeeze at either end, Tubarão or the Australian load ports. Nothing in what we’re tracking points to a delay problem, but we’re not ruling it out either. For now, the rally looks real and specific to iron ore, not evidence dry bulk broadly has turned.
Sources: handybulk.com (Baltic indices), shipandbunker.com (bunker/Brent), Doric Shipbrokers Weekly Market Insight (28.08.2026, own fixture records).